3PL Industry Trends, Benchmarks, and Market Analysis
The 3PL fulfillment industry is undergoing structural transformation as e-commerce volume growth, technology consolidation, and brand demands for operational transparency reshape how warehouse operators compete. Rising order volume keeps lifting baseline throughput requirements for 3PL operators, and brand clients now score those operators on real-time visibility and SLA reporting. Octup tracks the market size, adoption curves, and operational benchmarks that 3PL operators, investors, and brands use to position against these forces.
What is the current size and growth trajectory of the 3PL fulfillment market?
The global third-party logistics market reached $1,261.0 billion in 2025 and will grow at a 9.1% CAGR to $2,502.2 billion by 2033, according to Grand View Research's 2026 forecast. Fulfillment-specific 3PLs address a narrower subset of that market.
E-commerce brands use 3PL operators as outsourced fulfillment partners responsible for pick, pack, ship, and returns processing. Armstrong & Associates' 2026 segment breakdown values the U.S. 3PL market at $323.4 billion in 2025, up 5.0%. Headline figures overstate the addressable opportunity for warehouse-based fulfillment: the global 3PL sector revenue breakdown shows freight brokerage, transportation management, and asset-based trucking inflating the totals. Market Data Forecast's 2024 analysis reports the Value-Added Warehousing and Distribution segment held 49.3% of the U.S. third-party logistics market share in 2024, and operators should benchmark their competitive position inside that fulfillment segment, not against the broader logistics market.
The 3PL fulfillment market is driven by sustained e-commerce volume growth and brand outsourcing of logistics operations, with SKU proliferation compounding both. Three drivers move the number:
- E-commerce volume expansion. Global e-commerce sales crossed $6.8 trillion in 2025, with roughly 62% of those transactions relying on some form of third-party logistics assistance, according to Dataintelo's 2026 data. Technavio's 2026 outlook projects the U.S. 3PL market will add $146.8 billion from 2025 to 2030 at an 8.4% CAGR, with e-commerce fulfillment volume growth as the primary driver.
- Brand outsourcing acceleration. Dataintelo reports 74% of mid-market e-commerce brands outsourced at least one logistics function to a 3PL provider in 2025, up from 61% in 2022. Digital Commerce 360 reported in 2024 that e-commerce now accounts for 70% of many 3PLs' business portfolios.
- SKU proliferation. Expanding catalogs raise pick complexity, storage density demands, and the cost of every mis-pick, which pushes brands toward operators running mature warehouse management systems.
The 3PL industry is undergoing consolidation as mid-market and enterprise operators acquire smaller regional 3PLs to gain scale and client diversification. The competitive structure remains a fragmented mid-market pressed from above by private equity-backed roll-ups and large national operators. Vertical-specific 3PLs in apparel, health and beauty, and direct-to-consumer are gaining share against generalist operators, because category workflows such as garment-on-hanger handling, lot and expiry tracking, and branded unboxing reward dedicated operations.
Smaller independent 3PLs absorb consolidation pressure on three fronts: per-order pricing against scaled competitors, client expectations on SLAs and reporting that assume enterprise tooling, and a widening technology investment gap. The industry-wide margin and revenue reference data documents the unit economics separating scaled networks from regional independents.
Near-shoring and reshoring in manufacturing are creating new demand nodes for domestic 3PL fulfillment capacity, particularly in the Southeast and Midwest U.S. Operators weighing geographic expansion should score these emerging nodes against the traditional coastal gateway markets.
How fast are 3PL operators adopting technology, and what separates tech-forward operators from laggards?
Technology adoption is the primary competitive differentiator separating profitable 3PL operators from margin-compressed laggards. Adoption splits by operator size: large operators buy robotics and conveyor automation, mid-market 3PLs buy software-led efficiency, and tech-forward operators separate themselves through client-facing reporting and billing automation rather than warehouse management systems alone.
1. Automation investment follows operator scale. High-volume operators put capital into robotics, goods-to-person systems, and conveyor infrastructure that pays back on throughput. Mid-market 3PLs cannot justify that capital spend, so they chase software-led efficiency through better slotting logic, labor management, and process discipline on floors they already run.
2. SaaS migration replaces legacy WMS modules. SaaS platform migration applies to 3PL billing, analytics, and client-reporting workflows that operators previously managed in spreadsheets or legacy WMS modules. The emerging technology trends in 3PL operations track purpose-built billing engines, analytics layers, and brand-facing portals displacing those manual workarounds.
3. The separating gap sits in client-facing workflows. A warehouse management system controls the building; reporting and billing control the client relationship. A 3PL runs a capable warehouse management system yet still loses accounts to competitors offering real-time brand portals and automated invoicing, because brands buy visibility and billing accuracy as much as pick accuracy. The Octup operator analytics and trends measure operator performance across these workflows.
4. AI adoption is early-stage but accelerating. Operators apply machine learning to exception handling, demand signal interpretation, and anomaly detection rather than full autonomous decisioning. The 3PL technology evolution and AI trends document these deployments moving from pilot projects into production, with SaaS platforms carrying the capability down-market to mid-sized operators.
What are the industry benchmarks for 3PL operational performance in 2026?
Order accuracy rate has an industry benchmark of 99.5%+ for top-quartile 3PL operators, with median operators tracking closer to 98 to 99%. Four metrics define 3PL operational performance in 2026: order accuracy, SLA attainment, cost per order, and labor productivity measured in units per labor hour.
- Order accuracy: The gap between top-quartile and median operators comes from barcode validation at pick and pack, disciplined slotting, and WMS-directed workflows. Every tenth of a point below 99% surfaces as reships, credits, and client escalation calls.
- SLA attainment: On-time shipping attainment is measured against the contract cutoff, and the benchmark shifts with carrier mix. Premium carriers and same-day cutoffs hold a narrower window than economy ground, and service credits attach when attainment slips below the contracted floor.
- Cost per order: Cost per order falls as volume rises because fixed overhead and automation spread across more orders, so flat industry averages mislead small and mid-size operators whose per-order labor share runs higher. Digital Commerce 360 reported in 2024 that 22% of 3PL respondents offering e-commerce fulfillment and FBA Prep saw high profitability growth, versus 17% across other fulfillment types, and that 3PLs served an average of 3.9 industries.
- Labor productivity: Units per labor hour is the standard throughput measure on the floor. Automation moves the metric directly because goods-to-person systems, put walls, and conveyor sortation cut travel and touches per unit.
Published benchmark data carries self-reporting bias. Operators who participate in benchmark surveys tend to be more tech-forward, so published averages underrepresent the true median. Operators should calibrate targets against their own client mix and volume tier. The industry-wide 3PL performance thresholds provide the starting grid, and comparing your metrics to peer operators at the same tier yields defensible targets.
Returns processing is growing as a share of 3PL workload, driven by DTC and apparel clients. Returns as a percentage of outbound volume is an emerging operational metric worth tracking alongside traditional throughput KPIs.
How are sustainability and ESG requirements reshaping 3PL fulfillment operations?
Sustainability and ESG requirements reshape 3PL fulfillment operations through four pressure points: brand clients write sustainability clauses into service agreements, demand packaging waste reduction, request carbon footprint disclosures, and favor 3PL operators whose waste-reduction programs also lower operating costs.
1. Contract renewal now carries ESG conditions. ESG compliance is becoming a contract-renewal criterion for brand clients evaluating 3PL partners, especially mid-market and enterprise e-commerce brands. Procurement teams at mid-market and enterprise brands score 3PL operators on emissions data, packaging practices, and facility energy programs before renewing service agreements.
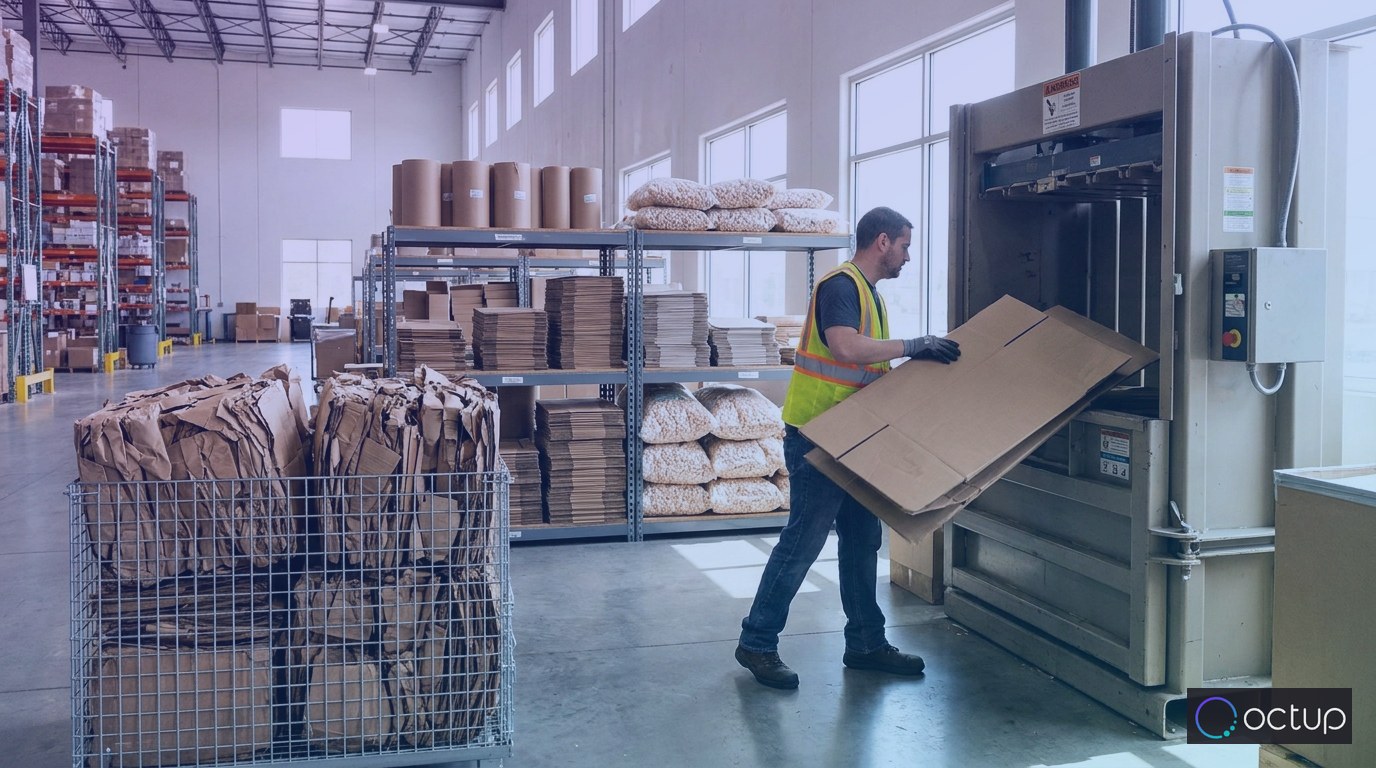
2. Packaging waste reduction is a stated client expectation. Brand clients demand right-sized cartons, recyclable and recycled-content materials, and the elimination of single-use plastics from outbound shipments. Packaging engineers at 3PL facilities now audit corrugate grades and void-fill usage against brand scorecards, not just against damage rates.
3. Carbon footprint reporting has moved into the RFP. In 2026, brand clients ask 3PL operators to track and disclose transportation emissions, facility energy consumption, and packaging impact by lane, site, and material type. The ESG frameworks applied to fulfillment most often in brand scorecards are the GHG Protocol's Scope 3 categories, CDP supply chain disclosures, and EcoVadis ratings, so a 3PL operator's reporting stack must map to all three.
4. Cost pressure and ESG investment often align. Sustainability programs that reduce waste frequently generate measurable cost savings for 3PL operators: right-sizing cuts corrugate and void-fill spend, shipment consolidation cuts fuel cost per order, and efficient conveyors and lighting cut facility energy bills. Waste is a line item before waste is a metric, and cutting waste improves margin whether or not a brand client audits the result. Energy cost exposure remains one of the most underreported ESG-adjacent risks for 3PL operators. Facility energy spend keeps rising as a share of revenue, and operators without energy management programs absorb margin compression that sustainability investments could partially offset.
Sources
- Market Data Forecast, "U.S. Third-party Logistics (3PL) Market Size & Growth, 2034" (2024)
- Grand View Research, "Third-Party Logistics Market Size & Share Report, 2026-2033" (2026)
- Technavio, "US Third-party Logistics (3PL) Market Growth Analysis - Size and Forecast 2026-2030" (2026)
- Dataintelo, "E-commerce 3PL Market Research Report 2034" (2026)
- Digital Commerce 360, "Ecommerce drives growth for 3PL providers amid industry challenges" (2024)
Octup

About the Author: Alon Partuk
Alon Partuk is Founder & CEO at Octup. Alon built Octup after seven years in D2C, scaling his brand Apricoat into a multi-million dollar company — where he lived the 3PL pain firsthand: missing visibility into inventory, marketing performance, and SKU-level costs. He launched Octup in 2022 as the first platform to unite warehouse intelligence with billing automation, purpose-built to close the gaps WMS platforms leave behind. Connect with Alon on LinkedIn.
Related Posts

